Federal Foreclosure Moratoriums’ Effect on Housing Prices
Jason M. Hunter | June 28, 2021
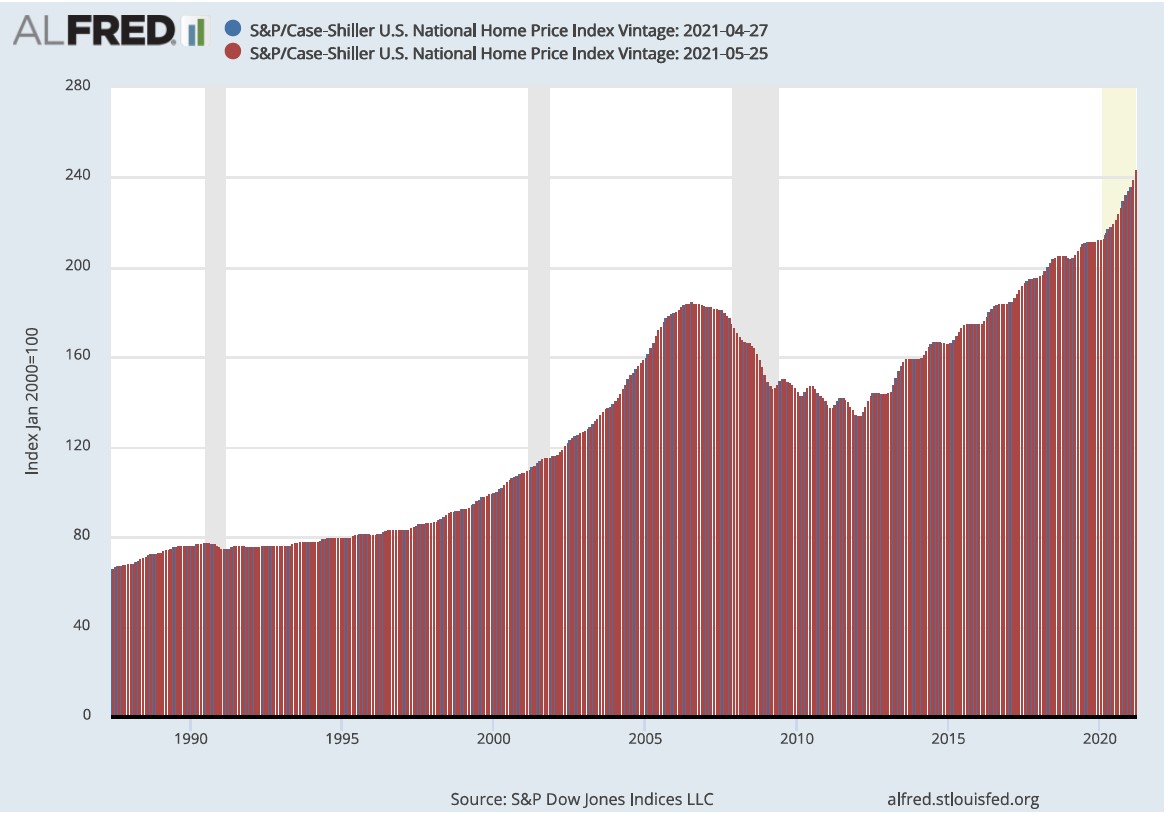
It seems apparent that price trends in housing remain unsustainable. The S&P CoreLogic Case-Shiller 20-metro-area house price index has steadily risen since the middle of last year and has averaged 11% growth thus far in 2021.[i] In fact, home prices have never been higher. The median existing-home sales price in May topped $350,000 for the first time, the National Association of Realtors said Tuesday. That figure is nearly 24% higher than a year ago, the biggest year-over-year price increase NAR has recorded in data going back to 1999.[ii] All of this to the resultant frustration and exclusion of younger would-be buyers.[iii]
Part of price growth is tied to interest rates, which are being kept artificially low due to the Fed’s continued purchases of mortgage-backed securities, but rates appear to be only part of what’s happening.[iv] Current reports estimate that due to years of underbuilding the U.S. housing market has a deficit of around 5.5 million units.[v] Thus, clearly, inventory is also an issue driving prices. Which brings us to the current federal moratoriums on foreclosure and the effect they have in exacerbating a lack of available homes.
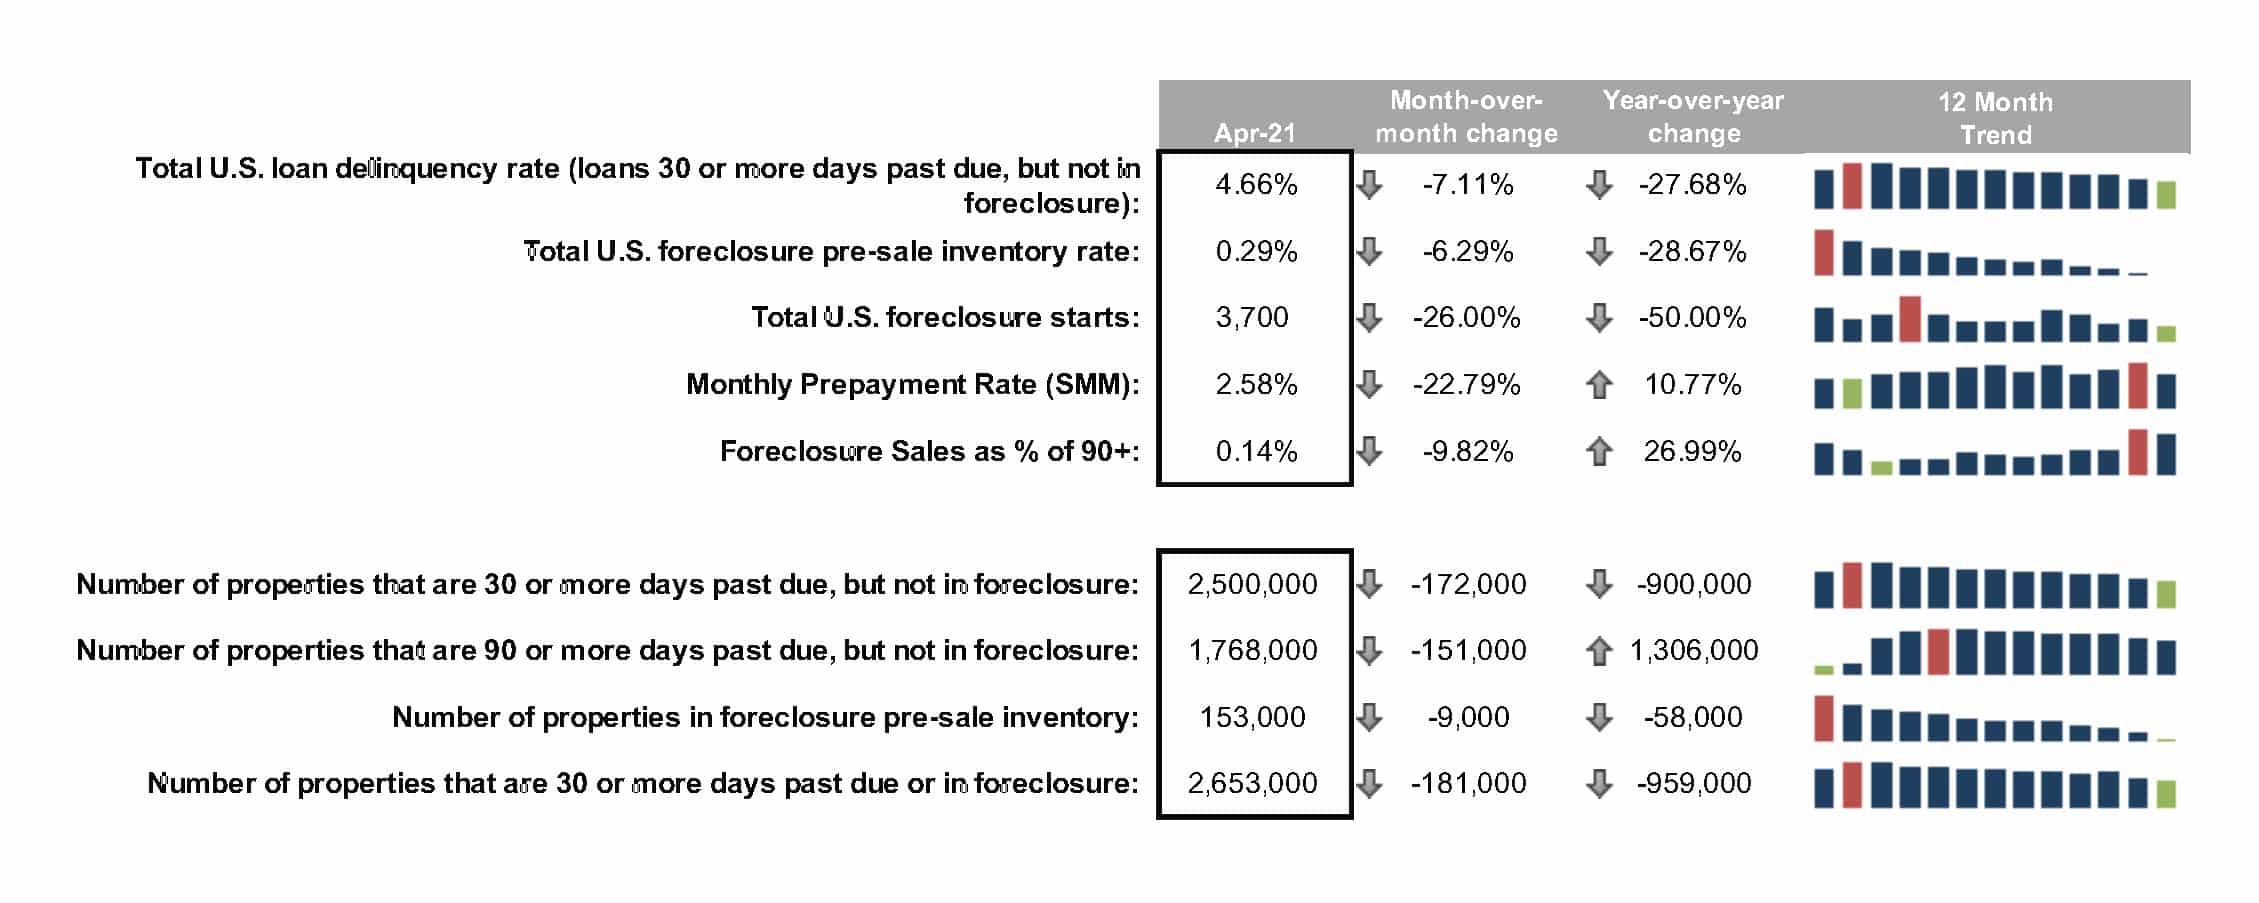
While it is no one’s wish to address a shortfall in housing exclusively through judicial sales, foreclosures serve an important role in our economy by allowing for the turnover of properties. All government programs have winners and losers, and some first-time buyers may find opportunities when the moratoriums are allowed to expire. As of this writing, an estimated 2.1 million homeowners remain in forbearance plans.[vi] Overlapping the forbearance numbers, 2.5 million properties are 30 or more days past due and an additional 1.7 million remain 90 days or more past due, none of which are in foreclosure.[vii] These numbers of course represent a significant portion of the shortfall mentioned earlier.
The prevention of unnecessary foreclosures should be, and in my experience is, a paramount goal of everyone in the mortgage industry. The forbearance program appears to have been a success, shown by the many folks who have entered into it and have been able to subsequently resume payments. In fact, about two thirds of homeowners who signed up for some type of mortgage forbearance during the Covid-19 pandemic have exited the programs.[viii]
However, through this success it seems clear that the housing market is unwell. Despite a strong economic recovery and historically low rates, home sales are slowing. As Sam Khater, Freddie Mac’s Chief Economist noted, slower sales have yet to translate into a “weaker home price trajectory because the shortage of inventory continues to cause pricing to remain elevated.”[ix]
Forbearance rates have largely tracked along income quartiles per zip code.[x] It follows then that FHA borrowers represent the majority of the remaining loans in forbearance, indicating that many of these loans are secured by the types of homes sought out by first-time buyers. So many of whom have been stymied by the current housing market.[xi] As such, it may be prudent now or in the near future to allow the normal systems surrounding foreclosure to function in order to determine which are unavoidable. Losing a home is always and clearly a tragedy, but at some point those who wish desperately to become homeowners must be granted the opportunity.
References:
[i] https://www.wsj.com/articles/for-many-home-buyers-a-5-down-payment-isn't-enough-1162409518
[ii] https://www.wsj.com/articles/u-s-existing-home-prices-hit-record-high-in-may-11624371222
[iv] https://www.nytimes.com/2021/06/15/opinion/inflation-federal-reserve-powell-biden.html
[viii] https://www.housingwire.com/articles/forbearance-re-entries-making-life-difficult-for-servicers/
[ix] https://themreport.com/daily-dose/06-10-2021/mortgage-rates-fall-again
[x] https://libertystreeteconomics.newyorkfed.org/2021/05/keeping-borrowers-current-in-a-pandemic.html
[xi] https://www.wsj.com/articles/for-many-home-buyers-a-5-down-payment-isnt-enough-11624095181
- share:

